Buying an overseas company brings its banks, currencies, suppliers and approval habits into the UK group. Good integration gives the parent clear oversight without breaking the local arrangements that keep the subsidiary trading. This guide covers what to map first, how to split responsibilities, how to handle currencies and fraud risk during the changeover, and where an international payment provider fits.
The Day After Completion
Suppose a UK manufacturer has just acquired a German business. Overnight it has inherited euro supplier invoices, local customer receipts, a separate accounting system and a set of people who already know how payments get made there. The parent may already pay European suppliers in euros through its own bank.
Leave the two setups running side by side without coordination and the problems arrive gradually: duplicated banking relationships, no clear view of cash needs across the group, and reconciliations that take longer each month.
The goal isn’t to push every payment through one account. It’s a structure the combined group can actually work with, where everyone knows who approves what, which route each payment takes and where the records live. For groups making £10 million or more in international payments a year, small inefficiencies and avoidable conversions add up quickly.
Start With an Honest Inventory
Before changing anything, record how the acquired company receives, holds and sends money today. That means its bank and payment accounts, currencies held, customer receipts, supplier transfers, payment providers, authorised users and approval limits. Recurring obligations, transaction volumes, accounting systems and any route the business relies on day to day belong on the list too.
Each item needs a reason attached. An account that looks redundant from London might be the one used for local payroll or tax payments, and closing it would cause trouble quickly.
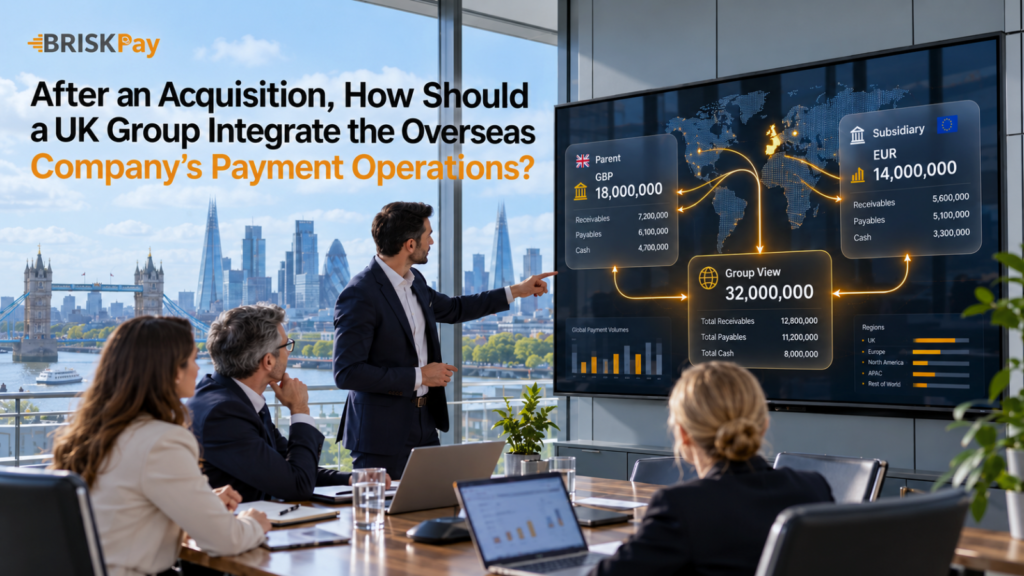
Here’s an illustrative picture of what the combined group might look like. The UK parent makes about £18 million in international payments a year in GBP, EUR and USD through two banking relationships. The overseas subsidiary adds roughly £12 million equivalent in EUR and USD through its own local provider. Together that’s around £30 million in international payments annually. (These figures are examples, not real company results.)
At the parent, the initial review would focus on cost and overlapping routes. At the subsidiary, the questions are about local needs and how currency flows in and out. Duplicated services, unexplained fees, manual approval steps and payments that regularly need someone to intervene should all be flagged. The inventory also becomes the baseline for measuring what later changes actually achieve.
Decide What the Group Owns and What Stays Local
With the inventory done, the parent and local finance need to agree who does what.
Group finance usually sets treasury policy, currency exposure limits and approval thresholds, oversees payment providers and defines consolidated reporting requirements. The local team is often better placed to forecast its own cash needs, validate invoices and supporting documents, run the arrangements it still needs locally and keep transaction-level records.
Write the split down. A short operating model should say who prepares, approves and releases each type of payment, and staff in both companies should be able to read it and know which account to use and what to do with an exception.
Ownership doesn’t grant account access. A UK parent can’t simply start using a subsidiary’s bank accounts because it owns the company. Account mandates, contracts, local rules and the group’s legal structure all shape what’s possible, so legal and finance should confirm the position before any payment responsibility moves between entities.
Use Existing Currency Before Buying More
Acquired businesses often earn and spend in the same currency. Say the German subsidiary collects €8 million a year from customers and pays €6 million to European suppliers. Some of those euro receipts could fund supplier invoices directly, depending on when money comes in, when bills fall due and what account arrangements exist.
Converting every euro receipt to sterling and then buying euros back for suppliers adds conversion costs for no real benefit. That said, holding foreign currency isn’t automatically the right answer either. Treasury still needs enough liquidity in each currency and has to accept the exposure that comes with holding it.
Three things help keep this under control. Compare customer receipts with supplier payments in the same currency to see how much naturally matches. Agree who can approve conversions and how rates and charges are judged. And track expected receipts, upcoming obligations and foreign-currency balances in one place.
To put a number on it, a one-percentage-point difference in exchange rate on a £10 million currency requirement is worth £100,000. That shows the scale involved; it isn’t a forecast or a promised saving. The currency approach should be written down and revisited as trading patterns settle after the deal.
Protect Payments While Roles Are Changing
Acquisitions bring new reporting lines, staff changes and unfamiliar procedures, which is exactly the environment fraudsters look for. Review existing account access and approval permissions before migrating any payment process.
Preparing, approving and releasing a payment should be separate steps, particularly for high-value transfers. Access should match what each person actually does, and the right to add a supplier shouldn’t carry the right to pay that supplier.
Supplier bank-detail changes need extra care. A new owner, an unfamiliar email address and a rushed approval are a familiar recipe for redirected payments. Verify any change through a contact method already on file, never through details supplied in the email requesting the change.
Sanctions checks need reviewing too. The UK’s Office of Financial Sanctions Implementation explains that UK financial sanctions apply to people in the UK and to UK-established legal entities, including their branches, wherever they operate. Other countries’ rules may apply to the subsidiary as well. The government’s financial sanctions guidance for importers and exporters sets out checks on counterparties, goods, services and payment chains, and should be used alongside the group’s own legal and compliance advice.
Picking Payment Services for the New Setup
The parent and subsidiary may well end up with different banks and providers. Replacing all of them straight away rarely helps. Work out which services support the intended operating model and which local arrangements still earn their place.
When comparing options, look at currency and destination coverage, transaction limits, transfer routes, payment tracking, FX pricing, fees, reporting and how delayed or rejected payments are handled. Ask how the provider deals with high-value payments and what documentation it needs.
A good international payment provider can handle cross-border transfers and currency conversion. It won’t set the group’s approval policy, consolidate its accounting records or decide how cash is allocated between subsidiaries. Those remain internal decisions.
Protection is worth understanding before large balances move. The FCA’s guidance on payment service providers explains the difference between safeguarding and Financial Services Compensation Scheme cover. Authorised payment institutions and electronic money institutions must safeguard customer funds, but safeguarding isn’t the same as FSCS deposit protection, and the exact position depends on the provider and service.
BriskPay offers international payments, currency conversion and multi-currency account options through its payment infrastructure and partners, which could form part of a group’s cross-border setup. The group should still check service terms, account eligibility, available currencies, payment routes and protections against its own requirements. BriskPay doesn’t replace a treasury function or accounting system. Its UK international payments page has the published service details.
The most useful business payment solutions are the ones that fit the group’s transaction profile, controls and reporting needs. Adding another platform to an already crowded setup rarely achieves that.
Moving Payment Flows Without Disrupting Trade
Suppliers, customers, payroll and tax authorities don’t pause for an integration, so changes need to happen in a sensible order.
A typical sequence runs like this:
- confirm the inventory of accounts and payment flows
- agree the operating model and responsibilities
- set up permissions and payment arrangements, and check access
- test transfers and the accounting entries they create, logging any exceptions
- move approved flows across in stages, with sign-offs and monitoring
- review processing and reconciliation results once the changeover settles
Test the full path before a new route carries real volume. Beneficiary details, references, currency amounts, approval permissions and the way fees show up on statements all need checking.
Cut-off times belong in the plan. The Bank of England’s CHAPS guidance states that CHAPS opens at 6am on working days and closes for bank-to-bank payments at 6pm, with customer payments normally submitted by 5.40pm, though individual providers can set earlier deadlines. Those times apply to CHAPS only. Euro, dollar and other currency payments follow their own provider, banking and market cut-offs, and local public holidays matter too.
Payments already in flight during the switch need a clear owner. Know which provider is responsible for each outstanding transfer and confirm its status before resubmitting anything, or the group risks paying twice.
Making the Records Line Up
A transfer confirmation doesn’t prove the accounting entry is complete. Each payment needs linking to the right legal entity, invoice and accounting period.
Agree consistent fields across the group: paying entity, beneficiary, reference, amount, currency, fees, status and settlement date, plus the exchange rate where it matters for accounting or treasury. Because conversions and intermediary banks can make the amount received differ from the amount sent, reconciliation should record and investigate those gaps instead of leaving unexplained variances in the ledger.
HMRC’s guidance on company accounting records says companies must keep adequate records to show and explain their transactions and support the preparation of accounts. It also covers the parent company’s responsibilities for subsidiary records in relevant circumstances.
Once the new processes have bedded in, go back to the baseline. Payment rejection rates, unexplained reconciliation differences, total transfer costs, processing times and the number of manual interventions will show where further changes are worth making, without assuming one setup suits every subsidiary.
Questions Finance Leaders Ask After an Acquisition
Q1. Must the acquired company replace its existing payment provider straight away?
A1. No. Assess how well the current service fits, any contractual commitments and the continuity risks first. A switch makes sense only when the replacement meets the business’s needs and the move has been properly tested.
Q2. Is cash pooling the same as integrating international payments?
A2. No. Payment integration is about executing and controlling transactions. Cash pooling brings balances together for liquidity purposes and carries its own legal, tax, banking and operational considerations.
Q3. Can every currency use the same payment route?
A3. No. Routes depend on the currency, destination, beneficiary bank and provider. A route that works for euro payments within SEPA may not suit a US dollar transfer elsewhere.
Q4. What should the parent ask the acquired finance team for on day one?
A4. A current list of accounts, authorised users, upcoming payment obligations, major suppliers, currency balances, outstanding transfers and critical payment deadlines. Access credentials should go through approved security procedures, never shared informally.
Q5. Can one payment platform handle transactions for several group companies?
A5. Possibly, depending on the legal entities, account arrangements, permissions and onboarding requirements the platform supports. Confirm that each subsidiary can use the service under the relevant terms.
Getting Back to Normal Trading
The test of a good integration is fairly simple: six months on, can someone in either finance team say which account pays a given supplier, who approves it and where the record sits? If the answer comes quickly, the structure is working. BriskPay’s international payment and currency services can carry part of that load, alongside the group’s existing banking, treasury and accounting systems.