Strong overseas sales can hide a cash gap when money sits in stock, production, shipping or unpaid invoices. For UK exporters, the fix starts with knowing how long each stage holds cash, why collections slow down and how receipts line up with supplier costs. This guide walks through the export cash cycle, shows how to put a figure on the cash tied up, and covers when outside funding makes sense.
Record Sales, Tight Cash
A UK manufacturer wins several large overseas contracts and posts another strong quarter. The factory is at capacity, orders keep coming and revenue is climbing. Yet the finance director is holding back on new spending because the bank balance isn’t keeping up.
The cash is usually somewhere between buying materials and getting paid. The company pays for components, funds production, books freight and sends the invoice. Then the customer takes another 60 days to pay. By the time the first order turns into cash, the business is already funding the next three.
Growth and cash shortage can happen at the same time. The useful question is where the money is held up, and why.
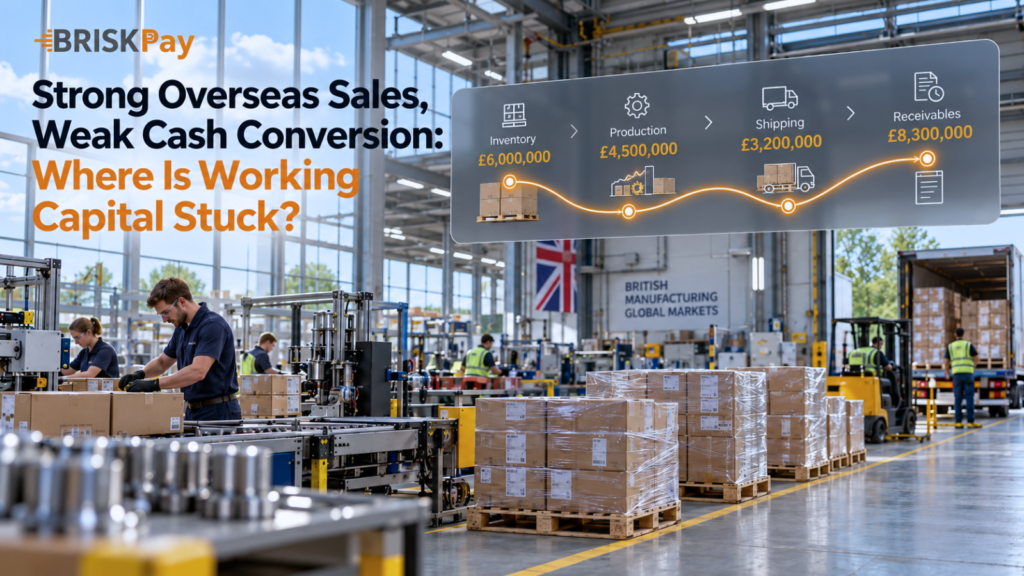
Following the Cash Through an Export Order
Money goes out at almost every stage of an export order before any comes back.
Purchasing comes first: materials, components and often supplier deposits. Long lead times or advance payment terms stretch this stage out. Production follows, with labour, energy and manufacturing costs, and delays or a build-up of work in progress keep cash locked up longer.
Shipping brings freight and export costs, and transit delays, customs issues or a missing document can all slow things down. Once the goods ship, the invoice goes out and revenue becomes a receivable. An error on that invoice, or a late submission, adds days before the customer even starts its approval process. Collection is the final wait, governed by credit terms, disputes and the customer’s own approvals.
Revenue and cash run on different clocks. A sale can qualify for recognition under the company’s accounting policy well before the customer pays, while production and operating costs still need funding today.
The government’s guidance on avoiding cash-flow challenges when exporting lists shipping delays, customs, longer payment terms and currency movements as common pressures. Sales figures alone can’t tell management how much funding the next round of orders will need.
Putting a Number on Slower Collections
Days sales outstanding (DSO) measures how long a business typically takes to collect on credit sales. A rising DSO can point to slower payers, longer terms or a change in the customer mix.
At export scale, a few extra days are worth a lot. Take a UK industrial supplier with £36 million in annual overseas credit sales. At a 60-day average collection period, roughly £5.92 million sits in receivables. Stretch that to 70 days and it’s about £6.90 million. At 80 days, it’s around £7.89 million.
Those 20 extra days tie up roughly £1.97 million more. The business has to fund that through existing cash, faster collections, additional finance or different trading terms.
The calculation is £36 million divided by 365, multiplied by the collection period. It assumes sales spread evenly through the year and ignores seasonality, VAT and credit notes, so treat it as a rough guide. Customer concentration and invoice timing can push the real figure either way.
Compare DSO with contractual terms too. A fast-growing business can carry a bigger receivables balance without anyone paying late. The detail sits in the invoices: which customers account for the increase, which amounts are overdue and what’s holding each one up.
Why Business Collections Stall
An overdue invoice doesn’t automatically mean the customer can’t or won’t pay. Plenty of delays come from admin.
An incorrect invoice, often a missing purchase order number or wrong details, simply needs correcting and the customer’s acceptance confirmed. A delivery dispute needs the contract, delivery and inspection records checked and the commercial issue resolved. An invoice stuck in the customer’s approval process needs someone to find out what paperwork is still outstanding. Sometimes the payment has actually arrived but hasn’t been matched, and tracing the transfer reference and remittance advice sorts it out.
Genuine financial pressure at the customer is a different matter. That calls for a look at payment history and credit exposure, and possibly a change to the payment arrangement.
The government’s guidance on managing non-payment when exporting makes the same point: find out why an invoice is unpaid before deciding what to do. It could be paperwork, a complaint, a quality concern or real financial difficulty.
Shipping documents deserve close attention. Under documentary collections or letters of credit, documents must meet the stated requirements before the transaction moves forward, and a small inconsistency can hold up payment from a customer who fully intends to pay. A large invoice stuck on a document error needs an operational fix, not tougher credit control. Sales, logistics and finance each have a part to play.
Business collections improve fastest when the process separates admin errors from credit problems, so effort goes where the delay actually is.
Stock and Supplier Terms Matter Just as Much
A company can collect faster and still feel squeezed if stock is building up or suppliers want paying sooner. The cash conversion cycle brings all three together:
Cash conversion cycle = inventory days + receivable days − payable days
Inventory days show how long stock sits before it’s sold. Receivable days show how long customers take to pay. Payable days show how long the business takes to pay its own suppliers.
Small shifts in each add up. If stock is held 12 days longer, customers take 20 days longer to pay and suppliers start demanding payment 10 days sooner, the cycle stretches by 42 days, even with sales unchanged.
Pushing supplier terms out can narrow the gap, but it isn’t always realistic. Suppliers may want deposits, charge for longer credit or have cash pressures of their own, and paying late can damage a relationship or disrupt the supply of critical parts.
For context, the Department for Business and Trade’s 2025 large-business payment statistics, published in July 2026, show large UK businesses took an average of 32 days to pay suppliers. Fifteen per cent of invoices by number were paid late, representing 14% of total invoice value. These figures describe large businesses paying their suppliers, not overseas buyers paying UK exporters, so they aren’t an export collection benchmark.
Purchasing, stock, customer terms and supplier obligations need reviewing together. Borrowing can cover a gap, but it won’t fix the process that created it.
Using Collected Funds Well
Getting paid is only half the job. Once the money lands, the company has to decide what to do with it.
Suppose a UK exporter collects €3 million from European customers and owes €1.8 million to European suppliers over the next two months. Converting all of it to sterling and buying euros back later adds conversion costs for no real reason. A better approach might be to keep enough euros for the supplier invoices and look at the remaining €1.2 million against other commitments, depending on timing, balances and treasury policy.
A foreign currency account gives UK exporters somewhere to receive and hold eligible currencies for exactly this purpose. BriskPay’s multi-currency account offering describes an arrangement for receiving and holding supported currencies, so a business in this position could keep the euros it needs for suppliers and decide on the surplus later.
The benefit comes from matching money already collected with real costs, not from guessing the next rate move. International collections work best when viewed alongside supplier commitments and expected receipts: what customers owe, what has actually arrived, which bills it can cover and which currency is needed next.
When a Working-Capital Facility Makes Sense
Some funding gaps are short and predictable. A big order may need heavy spending months before the customer pays. Others come from persistent late payment, excess stock or thin margins. These need different responses.
Fixing billing errors, resolving disputes and trimming stock deal with operational causes. External finance can bridge the gap between paying suppliers and collecting from customers, but its cost should be weighed against how long the gap lasts and why it exists.
Invoice finance is one route. The British Business Bank’s guidance on invoice finance explains how eligible unpaid invoices can unlock funding before customers settle. Depending on the facility, a provider may advance part of the invoice value, subject to eligibility, fees and contract terms. Look at the quality of the receivables, customer concentration, cost and obligations under the agreement. Factoring and invoice discounting also differ in who manages collections and the sales ledger.
Trade finance and other working-capital facilities may suit some exporters better. The government’s guidance on choosing export payment terms explains how advance payment, open account, documentary collections and letters of credit spread payment risk differently between buyer and seller.
Financing a one-off gap caused by a large order is a very different decision from borrowing month after month to cover invoice delays that could have been avoided.
What Management Should Be Watching
A single receivables total doesn’t show where cash is stuck. A useful monthly view tracks:
- DSO and overdue receivables, to see if collection timing is slipping
- inventory and work-in-progress days, showing how long cash sits before a sale
- supplier payment days
- disputed invoices by value, which point to commercial or admin blockages
- customer concentration
- available cash by currency, and the forecast funding gap
Trends tell you more than one month-end figure. Stable DSO with rising inventory days is a different problem from an unchanged production cycle with customers paying later.
Each team holds part of the answer. Sales can explain changes in credit terms, operations can flag production and shipping delays, and finance can surface rejected invoices and open disputes. Treasury then sets expected collections against upcoming payments and the currencies they’re due in.
Questions Finance Leaders Ask About Working Capital
Q1. Can a company post record sales while its cash position gets worse?
A1. Yes. Expansion ties more cash up in stock, production and unpaid invoices. Payment timing and operating costs decide how much liquidity is left.
Q2. Is DSO enough to judge working-capital performance?
A2. No. DSO covers receivables only. Inventory days and supplier payment days show the rest of the cash conversion cycle.
Q3. Should UK exporters always ask for payment in advance?
A3. No. Advance payment lowers non-payment risk but can make an offer less attractive to buyers. Terms should reflect the customer, market, deal size and relationship.
Q4. Does a foreign currency account improve cash conversion?
A4. Not directly. It helps manage funds once they’re collected, while cash conversion measures how long it takes to recover the cash invested in operations.
Q5. When should a business consider invoice finance?
A5. It can suit a business with a funding gap between delivery and collection on eligible invoices. Check the cost, terms, customer concentration and the reason for the gap first.
Find the Slowest Stage First
Before approving the next large overseas order, look past the margin and ask how much cash it will absorb before the customer pays, and for how long. Then find the single stage where money stays stuck longest. Sometimes it’s a recurring invoice error, sometimes stock bought too early, sometimes credit terms that crept out over time. Fixing that one stage usually frees more cash than any new facility.