A US customer stretching its payment terms can throw off a Canadian company’s CAD/USD forecast: the dollars arrive later, while payroll, supplier bills and financing costs stay on their original dates. Timing, currency exposure and funding all need updating together. This guide covers what to confirm with the customer, how to rebuild the forecast, what happens to existing hedges and how to cover the gap.
Sixty Extra Days on a US$20 Million Invoice
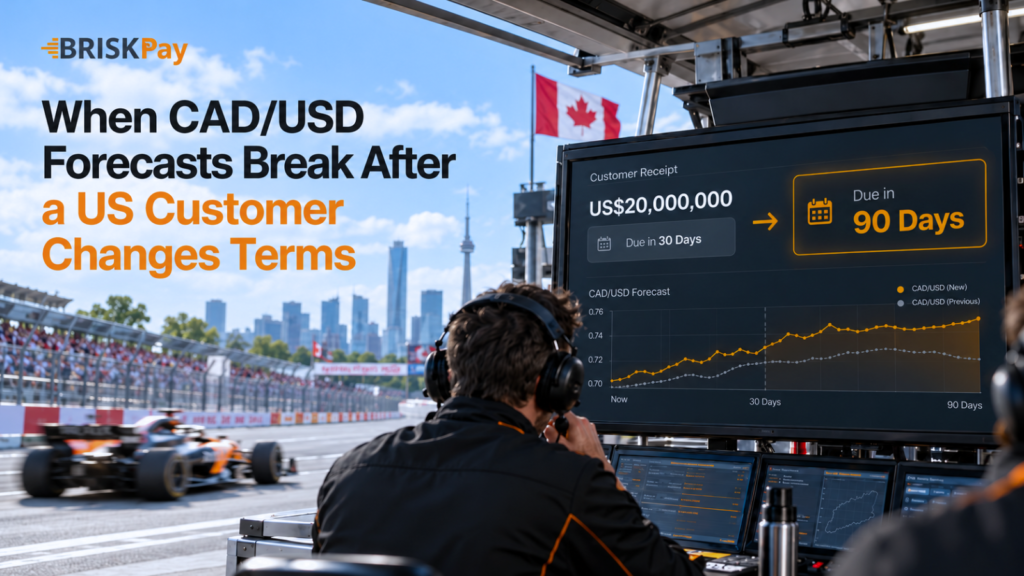
A Canadian manufacturer expects US$20 million from a major US customer within 30 days. Production costs are already paid, the next order is underway and treasury has earmarked part of the receipt for Canadian-dollar operating costs. Then the customer asks for another 60 days.
The sale is still good business. The financial plan, however, has changed. The company now has to carry its costs for two more months, and the dollar receipt stays exposed to exchange-rate moves for the same period. If a forward contract was already booked around the original date, or the proceeds were promised elsewhere, things get more complicated still.
So a change in terms is more than an accounts receivable issue. It affects cash availability, FX exposure, financing needs and the assumptions behind the company’s treasury management. For Canadian businesses with US$10 million to US$30 million in cross-border receipts, the response has to reflect the size of the exposure, the new date and the currency needed to keep operating.
First, Pin Down What Has Actually Changed
Start with the contract. A buyer asking for more time doesn’t change an agreed payment obligation on its own, so check the contract, purchase order and credit terms before accepting anything.
Export Development Canada notes that US buyers commonly expect open-account terms of 30 to 60 days, though arrangements vary. Longer terms mean the exporter carries the receivable longer and stays exposed to non-payment and currency risk for longer. EDC’s guidance on export payment terms covers the trade-offs.
Rather than just moving one line in a spreadsheet, finance needs answers to a handful of questions. Has the new due date been formally agreed, or is it still a request? Does it apply to the full invoice, or could part be paid earlier? Has the customer given a reason? Are future orders likely to slip the same way? And is this receivable already tied to an FX contract or a borrowing facility?
The reason behind the request matters a great deal. A reliable buyer dealing with a temporary admin issue is a different risk from one whose own cash is getting tight. Look at payment history and current exposure before extending more credit. EDC also recommends assessing buyer creditworthiness and keeping payment terms consistent across contracts and purchase orders.
Rebuilding the Cash Forecast
Sales forecasts might not change at all. The cash forecast definitely does.
Back to the US$20 million. The original plan had it arriving on day 30; the customer now proposes day 90. Canadian payroll, operating costs and domestic supplier payments are still due exactly as before. The USD balance stays lower for longer, and the funding plan has to cover a gap it was never built for.
Both the rolling short-term forecast and the longer projections need updating. The short-term view should show the exact dates receipts and payments are expected. The longer view should capture knock-on effects on borrowing, supplier commitments and planned investment.
BDC’s guidance on cash-flow management recommends forecasting cash in and out and testing scenarios such as a large new order, a cancelled order or losing a key customer.
Three practical questions should come out of the revised forecast:
- How much cash will be available before the customer pays?
- Which obligations fall due during the extra 60 days?
- What funding would be needed if the new date slips too?
The invoice value alone won’t answer these. Cash already held, other expected receipts, available credit and payments that can’t easily move all need to be in the picture.
How Much the Delay Exposes in Canadian Dollars
Payment timing and currency risk are tightly linked. A Canadian exporter that invoices in US dollars but pays its costs in Canadian dollars doesn’t know what a USD receivable is worth in CAD until it converts, unless it has hedged or has natural offsets.
EDC points out that FX risk can start as soon as a price is quoted in a foreign currency, not just at invoicing or payment. A longer wait before settlement gives the rate more time to move. Its guide to managing FX risk goes into this in detail.
To see the sensitivity, apply a few hypothetical USD/CAD rates to the US$20 million. At C$1.36 per US dollar, it’s worth C$27.2 million. At C$1.32, it drops to C$26.4 million. At C$1.40, it rises to C$28.0 million. A four-cent move either way shifts the result by C$800,000 before fees.
Neither move is more likely than the other. The point is how much the Canadian-dollar value of the same invoice can swing.
The Bank of Canada’s daily exchange rates are indicative reference rates based on financial-institution quotes. They’re useful for reviewing past movements and setting planning assumptions, but they won’t necessarily match the rate available for a real conversion. Keep the USD amount owed and its estimated CAD value as separate lines in the forecast, so different rate assumptions can be tested without treating any one of them as certain.
What Happens to an Existing Hedge
Hedges are usually built around an expected payment date. When the customer moves that date, the hedge and the receipt can drift apart.
Say the manufacturer has a forward contract to sell US$20 million for Canadian dollars on the original receipt date. The customer now pays two months later, but the contract still requires delivery of the currency on its settlement date, subject to its terms. The company may need to discuss an extension, an amendment, an offsetting trade or another arrangement with its provider. Each option can carry a cost or open a new exposure, and the right one depends on the original contract, current market conditions and the revised receipt date.
Other setups face their own version of the problem. Without any hedge, the receivable simply stays exposed until it’s converted or offset. A natural offset from USD expenses only works if the amounts and timing still line up. With a partial hedge, the hedged and unhedged portions need handling separately. And where one hedge covers several expected receipts, a delay on one invoice can unbalance the whole position.
Review the trade confirmation and talk to the bank or FX provider before changing anything. Avoid booking a fresh hedge just to restore the old plan until the revised exposure is confirmed.
Covering the Gap
A delayed US receipt can leave the company short of Canadian dollars despite a large amount owed to it. The first job is to size the shortfall and estimate how long it will last.
Several options are usually available, each with a cost.
Existing CAD cash keeps payments flowing but eats into reserves, so it suits companies with enough unrestricted liquidity. Other USD receipts from different customers can help, depending on timing and what else those dollars are needed for. Staged payment might work if the customer can release part of the amount sooner, though that needs an agreed change to the terms.
A credit facility can bridge a temporary gap, at the cost of interest, fees, conditions and borrowing capacity. Supplier timing is sometimes adjustable, provided relationships and contracts are respected. Receivables finance may be available if the transaction qualifies, with eligibility, pricing and recourse terms to check.
A business treasury team should size the gap first, then weigh borrowing against existing liquidity and the other options. A short delay from a solid customer may justify using cash on hand. Repeated extensions or a weakening payment record call for a wider look at credit limits and financing.
BDC notes that short-term financing can bridge gaps between receivables and payables, but its use should be grounded in the forecast and real operating needs. Credit conversations go better before the shortfall becomes urgent, while there’s still time to compare options properly.
Planning for More Than One Outcome
A forecast built on a single payment date gives a false sense of certainty. The revised plan should show what happens under a few different outcomes.
In the expected case, the customer pays on the newly agreed date and the gap is covered from planned resources. In a downside case, payment slips another 30 days and the forecast needs to show what that does to CAD liquidity and available credit. If the customer pays part first, the remaining receivable and currency exposure have to be recalculated. And if the customer disputes the invoice or shows signs of distress, credit risk, collection steps and funding assumptions all need revisiting.
Track what’s changed since the last review. A formal extension with a credible reason is not the same as an unconfirmed promise to pay. A partial payment helps, but the rest still needs watching.
Nobody can predict the customer’s next move. What the forecast can show is how much the business can absorb if things go differently. Set clear triggers, such as a missed revised date, another extension request, a drop in the customer’s credit quality or a funding threshold being crossed, and agree who in finance, sales or treasury reviews the position when one is hit.
Where Treasury Tools Fit
Once dates start moving, finance needs a clear view of balances held, receipts expected and obligations coming up in each currency. If that information lives across separate bank accounts, spreadsheets and payment providers, pulling it together takes time the team may not have.
Treasury solutions for businesses can bring currency balances together and connect treasury planning with payments and FX activity. What matters isn’t another dashboard. It’s seeing the position clearly enough to make a funding decision.
BriskPay’s treasury offering describes a unified view of multi-currency balances alongside payment and currency-conversion activity. A Canadian company working through a revised US payment date could use a suitable setup to review balances and plan how much currency to keep, transfer or convert, subject to service terms and supported arrangements. If that’s useful, a conversation with BriskPay can start from the currencies you receive, when your major payments fall due and how much visibility your finance team needs.
Questions Finance Leaders Ask About CAD/USD Forecast Changes
Q1. What should a Canadian company do first when a US customer asks for longer terms?
A1. Confirm the contractual position, understand the reason and check the customer’s credit. Then update the expected receipt date and review the effect on liquidity and currency exposure.
Q2. Does a delayed US-dollar receipt automatically mean an FX loss?
A2. No. The final CAD value depends on the rate when the exposure is settled or converted. A delay lengthens the exposure, but the rate can move in either direction.
Q3. What happens if a forward contract matures before the customer pays?
A3. The company may still have obligations under the contract. Check the confirmation and discuss options with the provider before changing or replacing the hedge.
Q4. Can USD supplier costs offset the risk on USD customer receipts?
A4. Yes, receipts and expenses in the same currency can offset each other when amounts and timing line up. Any remaining exposure still needs assessing.
Q5. Which exchange rate should a Canadian business use in its forecast?
A5. A documented planning assumption suited to the forecast’s purpose, tested against alternative rates. Bank of Canada daily rates are indicative; actual provider rates may differ.
Q6. How often should treasury update the forecast after a major customer changes terms?
A6. When the change is confirmed, and again whenever a material assumption moves, such as a missed payment, partial settlement or revised supplier obligation.
Keep the Hedge, the Forecast and the Contract Saying the Same Thing
A revised payment date changes three things at once: when cash arrives, what the dollars are worth in Canadian terms and how well any existing hedge still fits. The practical test is simple. Put the customer contract, the cash forecast and the hedge confirmation side by side, and check that all three show the same date and amount. Where they disagree, that’s the first thing to fix, before the revised terms turn a timing issue into a funding problem.