A month-end FX gain can lift reported profit without putting a single extra pound in the bank. For UK businesses holding foreign-currency receivables, balances or loans, the gain usually comes from revaluing something that hasn’t settled yet. This guide explains where these gains come from, why they don’t always help cash flow, how tax may be affected and what a useful month-end FX report should show.
A £300,000 Gain and the Same Bank Balance
A UK engineering group reports a £300,000 foreign exchange gain in its September accounts. Profit looks better. Yet a US customer still owes millions of dollars, supplier payments are coming up and the finance director wants to know how much money is actually there to pay them.
The answer depends on the balance behind the gain. An unpaid invoice, a dollar deposit and a foreign-currency loan can all produce exchange differences, and each has a very different effect on cash. For businesses handling £20 million or more a year across borders, corporate foreign exchange touches three things at once: reported results, the sterling value of overseas assets and liabilities, and the amount of each currency needed to keep trading.
Where the Gain Comes From
An exchange gain appears when a foreign-currency asset or liability is valued at two different rates. For a company reporting in sterling, that difference can change the carrying value of an item even though nothing has been paid or received.
Outstanding monetary items such as trade receivables, supplier payables and loans are generally translated at the closing rate on the reporting date. HMRC explains this in its guidance on foreign currency translation in company accounts.
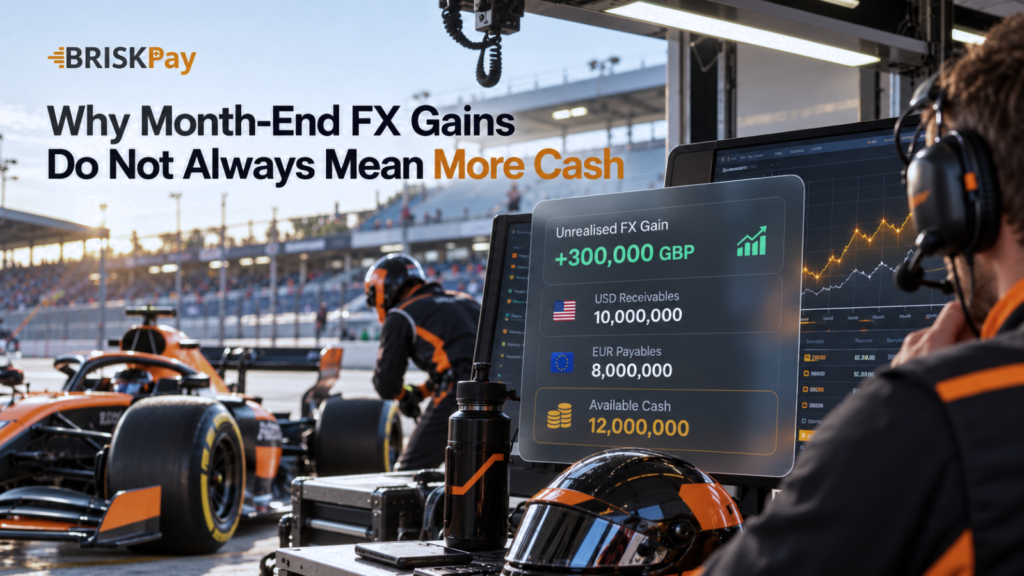
Here’s how that plays out. A UK exporter invoices a US customer for US$10 million, and the invoice is still unpaid at the end of September. At the invoice date, an illustrative rate of US$1 = £0.79 values it at £7.9 million. By month-end, the rate has moved to £0.82, so the same US$10 million is now carried at £8.2 million.
That £300,000 increase is recorded as an exchange gain, assuming the applicable accounting rules put it through profit or loss. Meanwhile the customer still owes exactly US$10 million and nothing new has reached the bank account.
HMRC confirms that exchange differences on monetary items generally go through profit or loss, with some exceptions. Its accounting guidance on exchange differences also explains that trading and financing differences can appear in different parts of the income statement.
The Same Rate Move Can Help One Balance and Hurt Another
Reading an FX gain without knowing which balance produced it can mislead. Take a stronger dollar against sterling, where sterling is the reporting currency and balances are unchanged.
A dollar receivable rises in sterling value, but cash only arrives once the customer pays. A dollar supplier payable also rises in sterling terms, which means settling it will cost more. A dollar bank balance gains sterling value while still holding the same number of dollars. And a dollar loan becomes larger in sterling terms without any cash coming in at all.
These are general patterns. Settlement activity, hedge accounting and other rules can change the specific result.
An importer with a US$10 million supplier liability could post an exchange loss from the same move that gives an exporter a gain. A group that both earns and spends dollars needs to look at both sides before reading anything into one favourable entry. Net currency exposure tells you far more than an isolated gain does.
A Bigger Sterling Number Doesn’t Pay Sterling Bills
A foreign-currency deposit is already money the company holds. Its sterling value moves with the rate, but the amount of foreign currency doesn’t grow from revaluation.
Suppose a group holds US$12 million in a business account. At US$1 = £0.79 it’s worth £9.48 million; at £0.82 it’s worth £9.84 million. That’s £360,000 more on paper, and still exactly US$12 million in the account.
Those dollars might cover US suppliers without any conversion. They won’t, by themselves, cover sterling payroll, tax or UK supplier invoices.
Consider an illustrative position across three currencies. The company holds £4 million against £5 million of upcoming sterling payments, leaving a £1 million gap. It holds US$12 million against US$4 million of dollar payments, so dollars are comfortably covered. And it holds €6 million against €7 million of euro payments, another €1 million short. Added together in sterling, the cash position might look healthy. In practice, the business still needs more pounds and more euros before certain bills fall due.
Treasury needs to see where funds sit, when they become available and which obligations they can actually meet.
Profit and Cash Are Reported for Different Reasons
The income statement records income and expenses under the applicable accounting framework. The cash flow statement explains how cash and cash equivalents moved. An exchange gain can raise profit without being cash generated from sales or collected from customers.
Presentation depends on the transaction. Differences on trading receivables and payables generally sit in profit or loss, while those on financing arrangements can appear in finance income or expense. Qualifying hedges and the translation of foreign operations can follow different rules again. The exchange effect on foreign-currency cash isn’t a customer receipt or supplier payment either, and cash flow reporting rules decide how it’s shown in the reconciliation of cash balances.
All of this matters when management compares results with budget. A gain from revaluing a long-term dollar loan says something quite different from better sales margins or a large customer payment. Good management reporting names the source of material exchange differences, so operating performance, exchange movements and actual cash generation can each be read on their own terms.
Does the Gain Affect Corporation Tax?
An accounting gain doesn’t automatically settle the tax answer. The treatment depends on the underlying asset, liability or contract and the relevant corporation tax rules.
HMRC explains that exchange gains and losses can arise at the period end and again when a monetary item settles; its guidance on the tax treatment of exchange gains and losses covers both. In most cases, the tax treatment follows the rules for the income, expense, asset or liability that produced the difference, a principle set out in HMRC’s guidance on giving effect to exchange differences.
Calling something an unrealised gain doesn’t settle its tax treatment. Loan relationships, derivative contracts, hedging arrangements and certain group transactions have their own requirements, so material or unusual items are worth confirming with tax advisers. Whatever tax position results should then go into the cash forecast with other tax liabilities and payment dates.
What Happens When the Customer Pays
The month-end calculation is only one point in the life of a transaction. When the customer pays, the company records the receipt and accounts for any further exchange difference between the previous carrying value and the settlement amount, subject to the applicable rules.
Say the US customer pays the US$10 million in October. The dollars land in the company’s account and some are later converted to sterling at the executed rate, with any charges applied. A business currency transfer like this moves money to where it’s needed. It’s a separate event from the revaluation that created the September gain.
The same logic applies when a currency exchange company quotes a conversion rate. The quote relates to a specific transaction on a specific day, while the closing rate measures outstanding balances under the company’s accounting policy. Different dates and purposes mean the rates can differ.
Transaction records should capture the amount and currency received, the amount converted, the executed rate, any fees and the settlement date. With those details, finance can reconcile the original invoice, the month-end valuation and the final proceeds without mixing them up.
What the CFO Should See in the Month-End FX Report
A total gain or loss figure on its own doesn’t help anyone decide anything. A more useful report answers five questions:
- Which receivable, payable, cash balance or contract produced each material movement?
- Which balances remain unsettled, and when are they expected to settle?
- How much is held in each currency, and how much of it is available to use?
- What was converted during the month, at what rate and with which charges?
- Which upcoming payments need more currency or funding?
The rates used for accounting also need a documented basis. HMRC’s guidance on exchange rates used in company accounts notes that companies use different sources, including bank rates and suitable external data. The London closing rate doesn’t automatically take priority for every purpose, and consistency matters more than the source.
With this kind of reporting, finance, treasury and senior management are all working from the same picture of open exposures and upcoming funding needs, which makes month-end discussions far shorter.
Questions Finance Leaders Ask About Month-End FX Gains
Q1. Are all foreign-currency assets revalued at the closing rate?
A1. No. Monetary items are generally translated at the closing rate, while non-monetary assets held at historical cost generally use the rate on the transaction date. Items measured at fair value can follow different rules.
Q2. Can an FX gain reverse next month?
A2. Yes. A later rate movement can reduce or reverse the gain before the underlying item settles.
Q3. Does an exchange gain always improve a borrowing covenant position?
A3. Not necessarily. It depends on how the financing agreement defines its covenants and how exchange differences feed into those calculations.
Q4. Can an unrealised gain affect corporation tax?
A4. It can, depending on the underlying transaction and the tax provisions that apply. Confirm the treatment of material items instead of assuming unrealised gains are excluded.
Q5. Which records support a month-end FX calculation?
A5. Invoices, loan agreements, foreign-currency amounts, the original and closing rates, the revaluation calculation, account statements and, later, settlement evidence.
Keep an Eye on the Receivable, Not the Gain
Until the US customer pays, the US$10 million receivable is the number that matters, and its sterling value can still move either way. Once the dollars arrive, the decision becomes practical: how much to keep in dollars for overseas suppliers and how much to convert for UK costs. BriskPay helps businesses with international payments and currency conversion at that stage, when money needs to move between currencies.