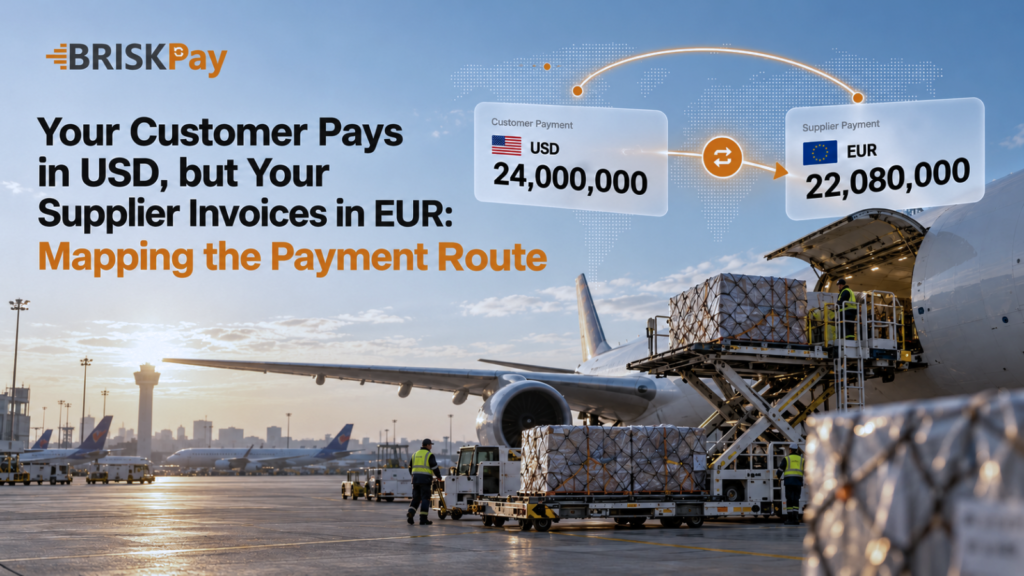
When a UK business gets paid in US dollars and pays its suppliers in euros, every order crosses two currencies before the money settles. This guide follows that route step by step: where conversion happens, how a small rate move changes the euro amount on a large balance, which costs to compare, and what to check before a high-value supplier payment goes out.
Two Currencies, One Margin
Picture a British manufacturer with £30 million of equipment sales to American customers. Its components come from Germany and the Netherlands. The sales contracts are priced in dollars and the supplier invoices arrive in euros. Somewhere between those two documents sits a conversion, a transfer and a timing gap, and each one can quietly change what the contract is worth.
The exchange rate gets most of the attention, but it’s only one piece. A customer who pays two weeks late, a transfer charge nobody budgeted for, or a supplier deadline that lands before the dollars arrive can all squeeze the same margin.
An online business account that can receive USD, convert it and send EUR makes the mechanics easier. The bigger gain, though, comes from understanding the route the money takes and the decisions made along it.
Why the Gap Between Dollars and Euros Costs Money
Agreeing to receive dollars and pay euros means taking on currency exposure. The USD/EUR rate keeps moving, so the euro value of a dollar receivable on the day the contract is signed is rarely its value on the day it gets converted.
Timing adds a second layer. An American customer on 60-day terms and a Dutch supplier on 30-day terms leave the business funding a month of euro costs before the matching dollars turn up.
Then there’s the cost of moving the money itself: FX margins, conversion charges, transfer fees and, on some routes, deductions by intermediary banks.
The British Business Bank’s guide to foreign-exchange risk explains how the time between agreeing a foreign-currency deal and settling it creates exposure, and it covers forward contracts, natural hedging and formal FX policies. For a company with more than £10 million in international trade, these questions belong inside its cash-flow and treasury controls rather than being handled invoice by invoice. Finance needs to know how much USD is expected, how much EUR is due and when each will move.
Following One Payment From Invoice to Settlement
It helps to trace a single transaction from start to finish.
The UK company invoices its US customer in dollars. The first check is a simple one: the currency, amount and payment terms on the invoice should match the contract.
Once the dollars arrive, finance reconciles the receipt and looks for anything deducted on the way in. A US$2 million invoice that lands as slightly less than US$2 million needs explaining before it’s matched in the ledger.
Conversion comes next. The dollars needed are exchanged for euros, and the figure worth judging is the total cost rather than the headline rate.
The euros then go to the supplier’s bank. Beneficiary details and payment requirements should be validated before release, particularly on a first payment or after any change to the supplier’s details. After the supplier confirms receipt, the amount is matched against the invoice and the transaction is recorded with its rate, fees and supporting documents kept together.
A dollar balance showing in the account doesn’t mean the euros for next week’s supplier payment are ready. Say a logistics group receives US$7 million a few days before a freight partner’s EUR invoice falls due. Finance still has to confirm the available balance, get a conversion quote, confirm the payment route and leave time for processing. Partial receipts, instalments and one customer payment funding several supplier invoices all make clear payment references more important.
What a One-Cent Move Does to a US$24 Million Balance
Large balances turn small rate changes into large sums. Take a company converting its full US$24 million balance into euros to cover €18 million of supplier invoices. The rates below are illustrative, not current market quotes, and they leave out fees.
- At US$1 = €0.92, the balance produces €22.08 million, leaving €4.08 million after the supplier invoices.
- At €0.91, it produces €21.84 million, leaving €3.84 million.
- At €0.90, it produces €21.60 million, leaving €3.60 million.
A drop from €0.92 to €0.91 takes €240,000 off the euro proceeds. At €0.90 the difference reaches €480,000. The supplier still expects €18 million either way, so the movement comes straight out of what the business keeps.
None of this is a profit forecast. The figures ignore transaction costs, other liabilities and the timing of receipts and payments. The Bank of England’s exchange-rate data is a useful reference for historical and daily rates, although the Bank points out that these are statistical rates, not commercial ones offered by providers. Use a market reference to judge a quote, then work out the real outcome from the rate you’re actually offered.
Four Ways to Get From USD to EUR
Convert directly. The company receives dollars and exchanges what it needs straight into euros. It’s straightforward when the provider supports both currencies and the payment destination, and the result is easy to check against supplier invoices. Straightforward isn’t automatically cheapest, though. The rate, any conversion charge and the outgoing payment fee have to be judged together.
Go through sterling. Some businesses have dollar receipts converted to pounds on arrival, then buy euros separately. Two conversions can mean two sets of FX costs. Then again, the company may need sterling anyway for payroll, tax and UK suppliers, so a fair comparison counts those needs alongside the euro bills.
Hold dollars until the invoice is due. Keeping USD gives treasury control over timing but leaves the future euro value uncertain. Holding balances under an agreed treasury policy is reasonable. Waiting purely in the hope of a better rate is a market bet.
Pay euros with euros. A company that also sells to European customers can use those euro receipts to pay European suppliers. Known as natural hedging, it reduces how much needs converting, provided the amounts and timing line up. It won’t remove the dollar-euro mismatch, but it can make it much smaller.
Compare Quotes by What the Supplier Receives
A low transfer fee can sit on top of a poor exchange rate. The cleaner test compares two numbers: what leaves your account and what reaches the supplier.
Ask each provider to quote on the same USD amount, EUR requirement and timing, and note:
- how many euros the dollars will buy, and how that rate compares with a market reference
- any separate conversion fee, receiving charge or outgoing transfer fee
- the chance of an intermediary bank deducting charges along the way
- the funding, verification and processing conditions that apply
Recording the quoted rate, every charge and the net amount for the supplier gives you a fair basis for comparing providers across repeated transactions. A €20,000 saving on one conversion looks good on paper, but it’s only repeatable if you understand the rate, fees and terms behind it.
When Dollars Arrive After the Euros Are Due
Suppose a UK importer receives US$8 million today, owes €5 million within ten days and expects another US$7 million in three weeks. The real question isn’t when to convert. It’s how to pay the euro bill without putting day-to-day liquidity under strain.
A workable process starts with a forecast of confirmed receipts and liabilities by currency and date, set against existing USD and EUR balances. From there, finance can calculate how much must be converted for upcoming invoices, test what an adverse rate move would do to cash, and set approval limits for large conversions and payments.
Forward contracts are another option for eligible businesses with predictable foreign-currency bills. They fix a rate today for a set future transaction, subject to the contract’s terms. Settlement requirements, pricing, any collateral or margin obligations and the consequences of the underlying invoice changing all need checking first. A hedge that no longer matches the real payment adds risk instead of removing it. The British Business Bank’s FX risk guidance covers formal currency policies in more depth, and large or complex positions justify proper treasury advice.
Getting the Euros to the Supplier
SEPA payments handle eligible euro transfers within the Single Euro Payments Area. The UK remains within the scheme’s geographical scope, as the European Payments Council confirms, although availability still depends on the provider, beneficiary and service.
SWIFT-based payments carry international payment instructions across a global network. SWIFT describes its own role as financial messaging. It doesn’t hold customer funds or manage accounts; the banks involved move and settle the money.
That difference matters because a sent instruction isn’t proof the supplier has cleared funds. Before a high-value payment goes out, check the beneficiary details, the supported route, charges and expected processing time, and allow for bank holidays, cut-off times and compliance checks. If the payment releases cargo, starts a production run or secures freight space, a day’s delay can cost more than the transfer fee.
What to Look for in the Account Setup
Three things tend to decide how well an arrangement works for USD receipts and EUR payments:
- Currency handling: receiving USD, holding foreign-currency balances where supported and converting to EUR at competitive rates
- Payment controls: clear fees, settlement times, approval steps and payment records
- Coverage: payment routes and service terms that suit the company’s volumes and supplier markets
BriskPay’s UK international payments platform supports cross-border payments through SWIFT, SEPA and local payment routes, alongside currency conversion. Businesses should confirm the currencies, pricing and settlement terms that apply to them.
Some companies use a specialist platform as a business banking alternative for selected international transactions and keep their existing bank for everyday operations. The right mix depends on currency needs, transaction volumes and internal controls.
Importers have one more point to keep separate. Customs valuation follows its own rules, and HMRC’s customs valuation guidance sets out the exchange rates used to convert foreign-currency amounts for customs purposes. Those rates have nothing to do with the commercial rate you get when converting.
Frequently Asked Questions
Q1. Can a UK business receive USD and pay suppliers in EUR?
A1. Yes, as long as its account or payment arrangement supports USD receipts, the EUR conversion and the outgoing supplier payment.
Q2. Is converting directly from USD to EUR always cheaper than going through GBP?
A2. No. Compare the total costs and net euro proceeds of both routes using the same amounts and timing.
Q3. Does a multi-currency account remove exchange-rate risk?
A3. No. It lets the business hold different currencies, but the value of dollars against euros keeps moving.
Q4. Which records should the finance team keep?
A4. Invoices, conversion confirmations, applied rates, charges, payment references and settlement evidence, alongside the relevant accounting and trade records.
Q5. Are SEPA transfers always faster or cheaper than SWIFT payments?
A5. Not necessarily. Route, cost and timing depend on the destination, the provider and the receiving bank.
Q6. Does a company need to replace its bank to handle international payments?
A6. No. A specialist payment platform can sit alongside an existing bank if the combined setup meets the company’s needs.
Start With the Next Euro Invoice
Take the next large EUR supplier invoice and trace it backwards: which dollar receipt funds it, when that money lands, where it gets converted and what the whole route costs. Doing that once usually shows where money is leaking. The best business account for this kind of trade is the one that makes that trace short, cheap and easy to evidence.